The facts
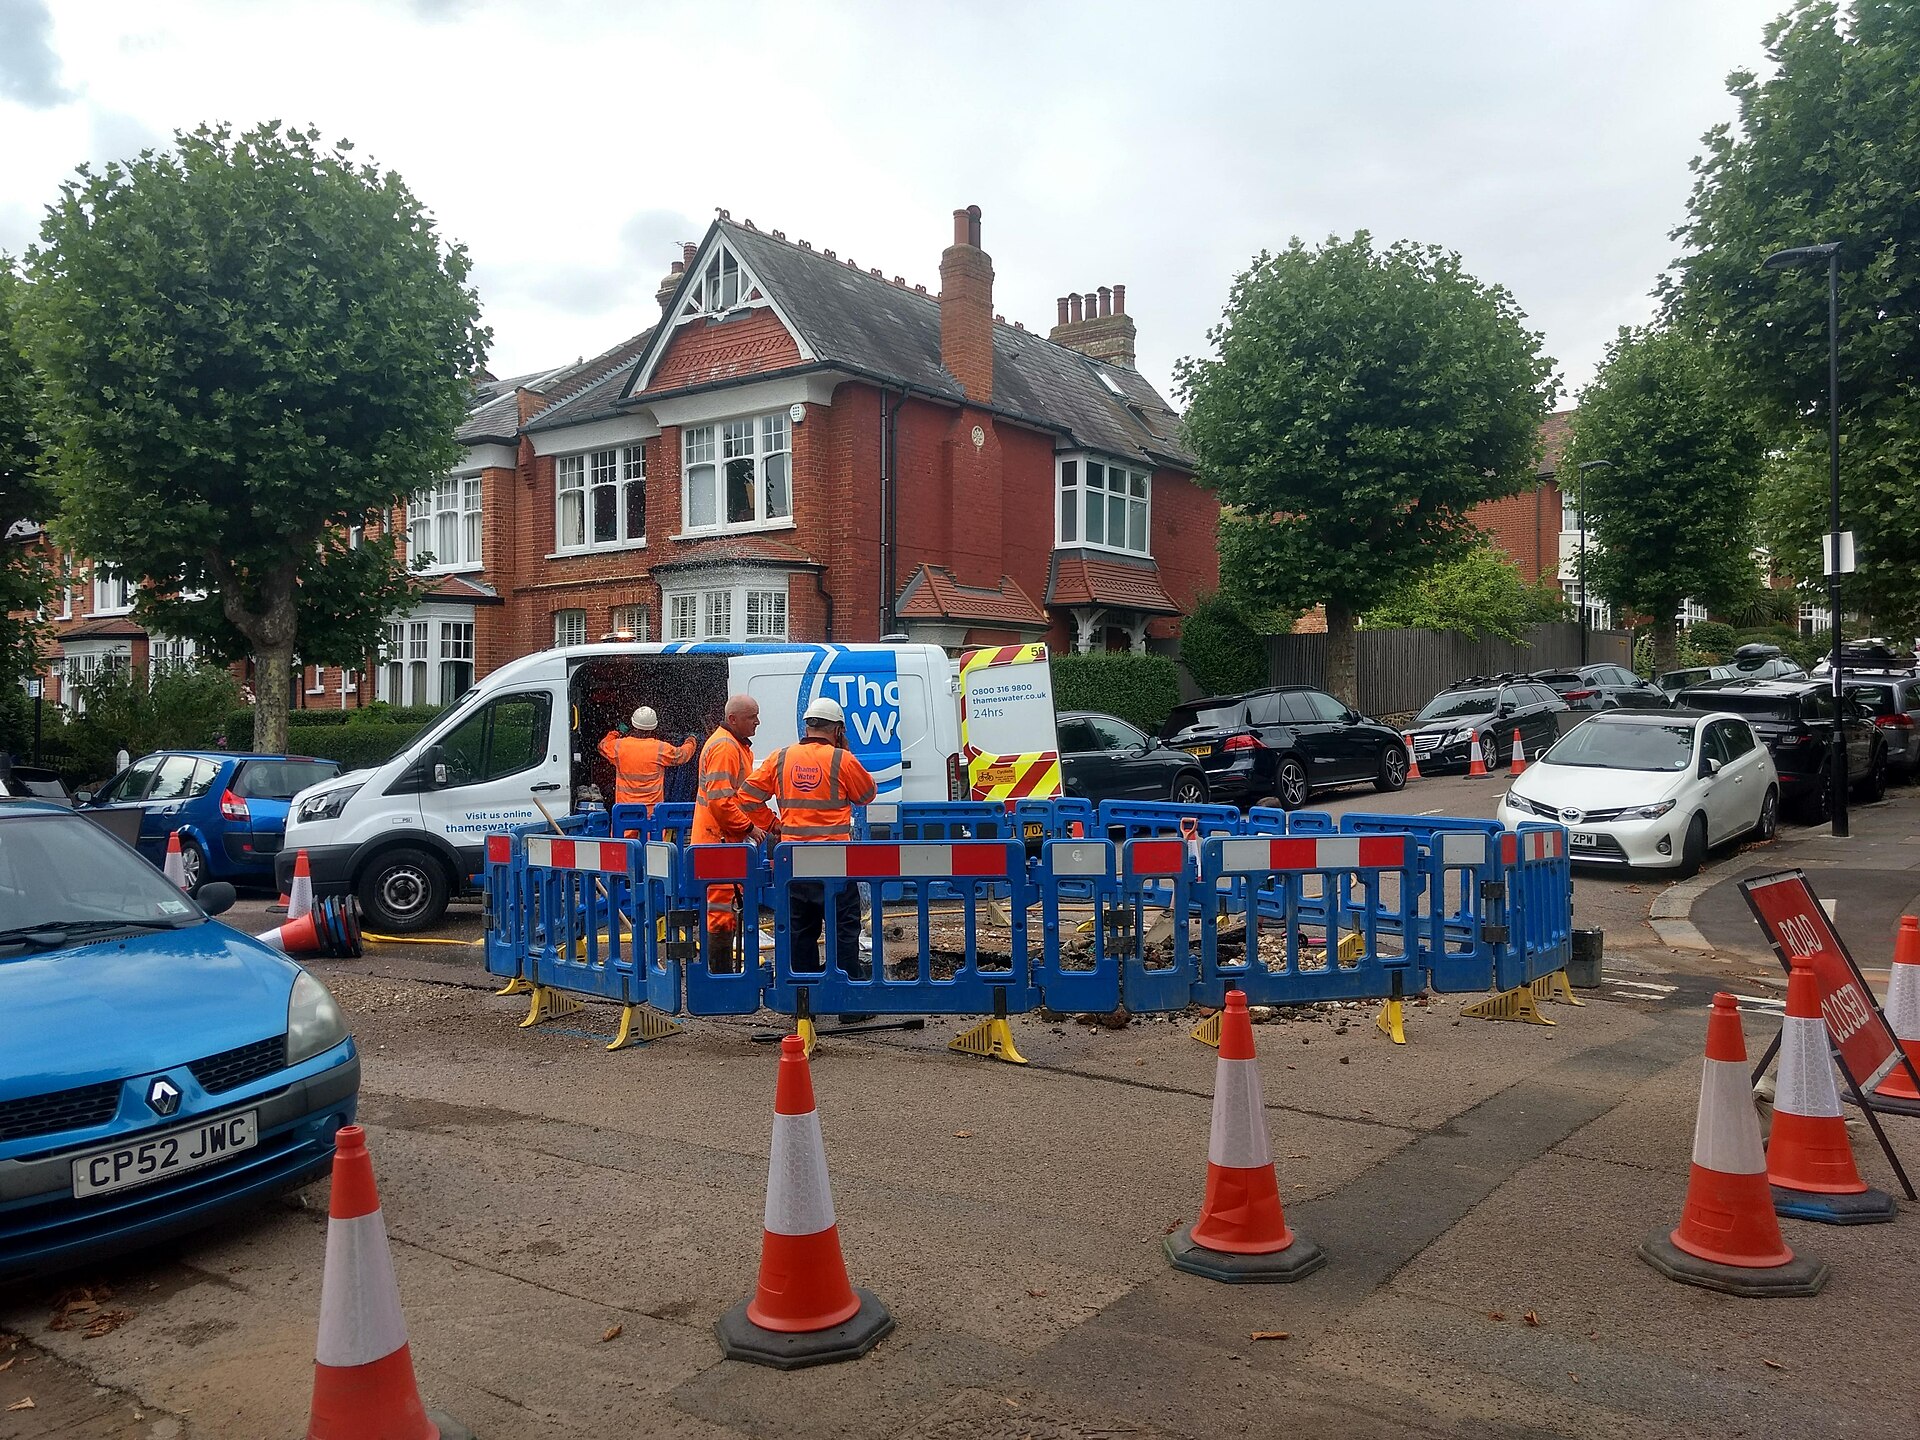
London & Valley Water, a consortium of Thames Water’s class A creditors that includes BlackRock, Elliott Management and Silver Point Capital, will vote on Thursday on a £2.4bn emergency loan. The loan would raise the company’s funding facility to £5.4bn and is intended to keep Thames Water operating through autumn 2027. Thames Water told creditors it could run out of cash by the end of 2026 or the start of 2027 without the injection. The utility has already drawn £2.65bn of a previous £3bn “super‑senior” loan at 9.75% interest. Campaign group We Own It calculated that, if the new loan were added to household bills on the same terms, it could cost about £40 per household in interest, or up to £454 if the full amount were passed on. Both Thames Water and the London & Valley Water consortium say the rescue financing will be borne entirely by the class A creditors and will not be added to customer bills. Andy Burnham, the Mayor of Greater Manchester, is weighing options that include creditor takeover, nationalisation or placing the company into special administration.
Our take
Here’s the beautiful fucking symphony of privatised failure: Thames Water is so spectacularly broke it’s having to beg the same vulture funds it already owes for another £2.4bn just to keep the literal shit flowing until 2027. These cunts have already mainlined £2.65bn of a ‘super‑senior’ loan at a cool 9.75% interest, a rate usually reserved for Colombian coke barons or your mate Dave’s payday loan. Now they’re back at the trough, snout first, for a top‑up that would bring their total credit line to a staggering £5.4bn. That’s not a utility balance sheet, that’s a national debt for a company whose main job is to stop your bathwater tasting of Victorian effluent.
And who are these generous philanthropists? London & Valley Water, a consortium of class‑A creditors featuring such humanitarians as BlackRock and Elliott Management - firms famous for their deep concern about your water pressure and not, say, stripping assets and flipping the corpse. They’re voting on whether to throw good money after bad into this financial septic tank. The utility’s promise? That this rescue loan will be borne ‘entirely’ by these lovely creditors and won’t be added to your bill. Right, and the Thames is made of single‑malt whisky. A campaign group did the maths: if this loan were passed on at the same usurious 9.75%, it could slap an extra £40 per household in interest, or a full £454 cunt‑punch if they just billed you for the whole thing.
Let’s be clear: this isn’t a turnaround, it’s a life‑support system powered by a payday lender’s desk. They’re not fixing the leaks; they’re just pouring more borrowed cash into the bucket to delay the moment the whole rotten structure collapses into special administration. Andy Burnham is over there scratching his head about whether to let these creditors take over, nationalise the shitshow, or put it into administration - which is like deciding whether to treat a gangrenous limb with a band‑aid, amputation, or thoughts and prayers.
So the next time you pour a glass of water and it smells faintly of financial despair, remember: a bunch of hedge fund dickheads are voting on whether to keep this corpse twitching for two more years, using money they’ll eventually try to wring from your piss‑poor wallet. It’s a perfect, stinking monument to privatisation: a vital public service now just a pinball between bankrupt management and their own loan sharks, with you holding the mop.